Free shipping on orders over 19,990 Ft via Packeta, Fox Post Box, and DPD Collection Point

Become part of a community of book lovers from all over the world and get access to a whole bunch of benefits.
Create an account for free
Free delivery for purchases over 19 990 Ft
DPD point 990 Ft
DPD courier 1 190 Ft
GLS point 1 190 Ft
Hungarian Post 1 795 Ft
Hungarian Post 1 690 Ft
Hungarian Post 1 690 Ft
FoxPost 1 190 Ft
Packeta point 1 190 Ft
GLS courier 1 690 Ft
 Contact
 How to shop

Help
Delivery
DPD point 990 Ft
DPD courier 1 190 Ft
GLS point 1 190 Ft
Hungarian Post 1 795 Ft
Hungarian Post 1 690 Ft
Hungarian Post 1 690 Ft
FoxPost 1 190 Ft
Packeta point 1 190 Ft
GLS courier 1 690 Ft
Free delivery for purchases over 19 990 Ft
Shopping guide
We’re here for you!
+36 9 6998 040
My account
▸
Empty :-(
0
Free shipping on orders over 19,990 Ft via Packeta, Fox Post Box, and DPD Collection Point
Markov-Switching Vector Autoregressions
Modelling, Statistical Inference, and Application to Business Cycle Analysis
Language
 English
Book
Paperback
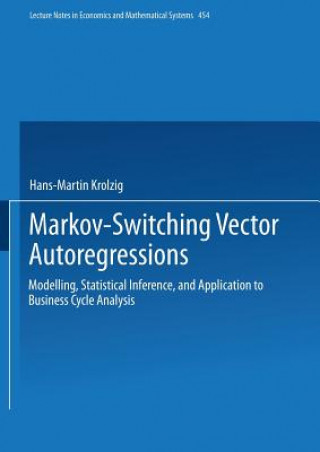
A discussion of Markov-switching vector autoregressions. It covers issues such as the state-space re...
Full description
Libristo code: 06617566
?
 244 b
244 b
36 632
Ft
In stock at our supplier
Shipping in 5-8 days
Up to 30 days for returns
Customers also purchased


A discussion of Markov-switching vector autoregressions. It covers issues such as the state-space representation, forecasting MS-VAR processes, multi-move Gibbs sampling, and co-integration analysis of VAR models with Markovian shifts in regime.
Actress
&
Polyglot
EWA KASP
for
Play video


Libristo has the largest selection of foreign-language books. That’s why I buy my books there.
About the book
Full name
Markov-Switching Vector Autoregressions
Author
Hans-Martin Krolzig
Language
English
English
Binding
Book - Paperback
Date of issue
1997
Number of pages
357
EAN
9783540630739
ISBN
9783540630739
Libristo code
06617566
Weight
918
Dimensions
297 x 210 x 20
Categories

Give this book today
It's easy
1 Add to cart and choose Deliver as present at the checkout 2 We'll send you a voucher 3 The book will arrive at the recipient's addressYou might also be interested in


Book advisor Libroamiko
By using this chat, you are communicating with generative artificial intelligence. By using it, you also agree to the processing of personal data.
Hi! I'm Libroamiko, your book advisor.
How can I help you?
Hi, I'm Libroamiko, can I help?